EV Battery Recycling Market (2024-2031)
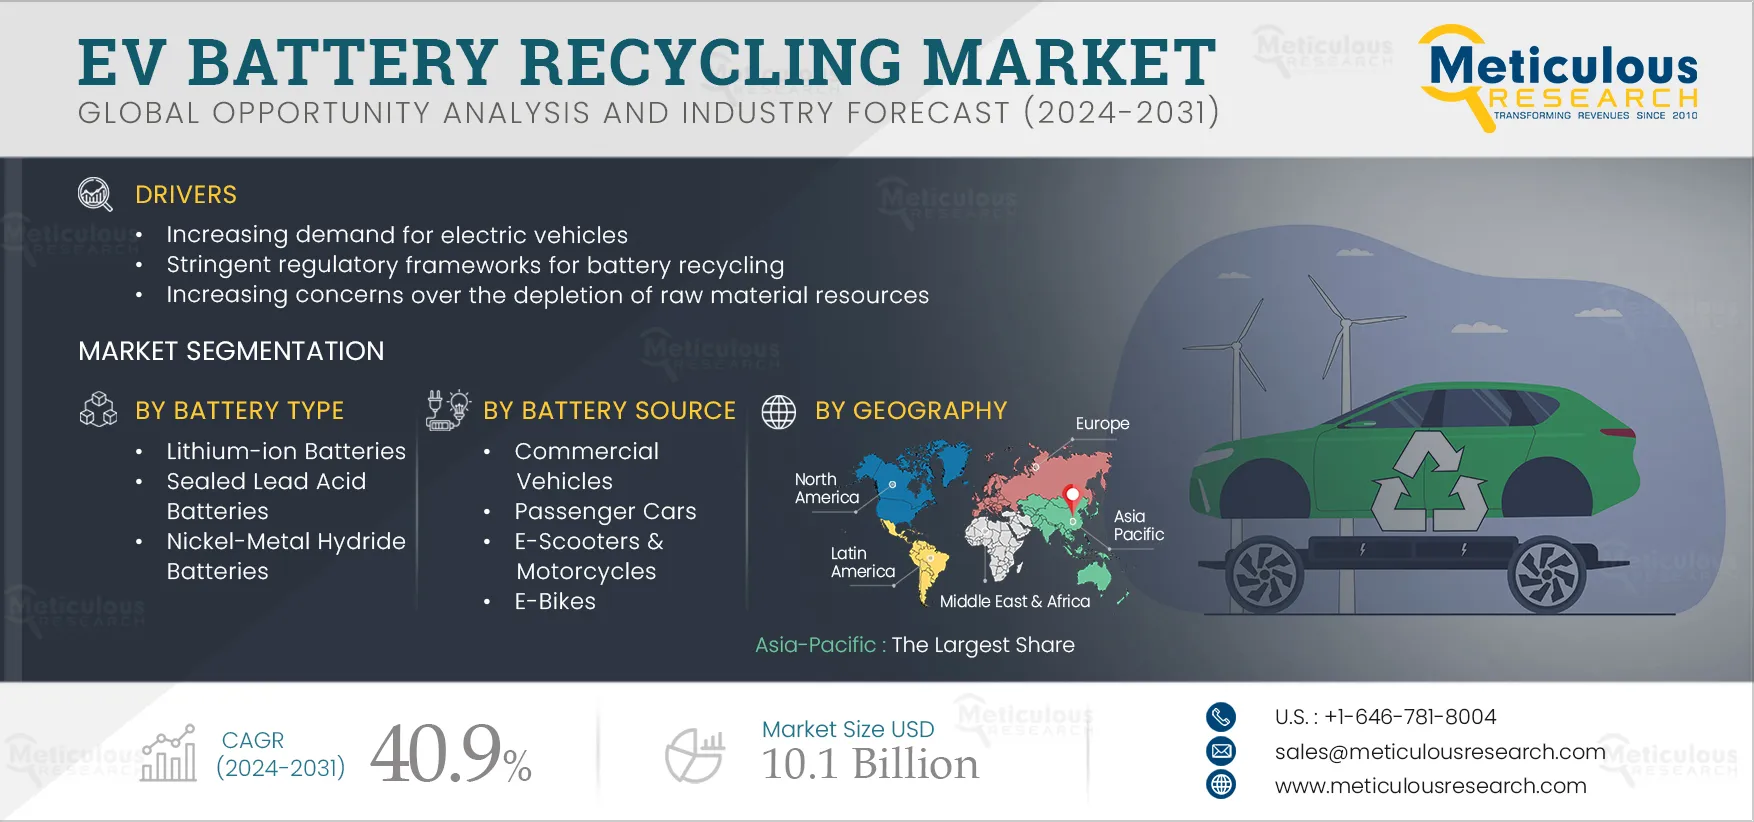
The EV Battery Recycling Market was valued at $0.72 billion in 2023. This market is expected to reach $10.1 billion by 2031 from an estimated $0.91 billion in 2024, at a CAGR of 40.9% during the forecast period 2024-2031. EV Battery Recycling Market Size & Forecast The growth of the EV battery recycling
- Published
- Sep 2024
- Pages
- 330
- Format
- PDF + Excel
- Report ID
- MR-799
- Base year
- 2023
- 2023 · BASELINE
- $720.0M
- 2031
- $10.10B
- CAGR 2024–2031
- 40.9%
2023 baseline · 2024–2031 forecast at 40.9% CAGR · hover a bar for the value
Key highlights
By Battery Type: The Lithium-ion Batteries Segment to Dominate the EV Battery Recycling Market in 2024
By Battery Source: The E-bikes Segment to Dominate the EV Battery Recycling Market in 2024
By Recycling Process: The Pyrometallurgical Process Segment to Dominate the EV Battery Recycling Market in 2024
By Business Model: The Contractual Recycling Services Segment to Dominate the EV Battery Recycling Market in 2024
By Material: The Graphite Segment to Dominate the EV Battery Recycling Market in 2024
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 330 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 40.9% |
| Market Size (Value) | $10.1 Billion by 2031 |
| Segments Covered | By Battery Type · Lithium-ion Batteries · Sealed Lead Acid Batteries · Nickel-metal Hydride Batteries · Other Batteries · By Battery Source · Commercial Vehicles · Heavy Commercial Vehicles · Light Commercial Vehicles · Passenger Cars · Battery Electric Vehicles · Pure Hybrid Electric Vehicles · Plug-in Hybrid Electric Vehicles · E-scooters & Motorcycles · E-bikes · By Recycling Process · Direct Physical Recycling Process · Pyrometallurgical Process · Hydrometallurgical Process · Other Recycling Processes · By Business Model · Contractual Recycling Services · Direct-to-Market Recycled Materials · By Material · Graphite · Nickel · Cobalt · Copper · Manganese · Lithium · Aluminum · Iron · Plastics · Other Materials |
| Countries Covered | Europe (Germany, U.K., Italy, France, Spain, Switzerland, Belgium, Norway, Poland, Finland, and Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Singapore, Australia & New Zealand, Malaysia, and Rest of Asia-Pacific), North America (U.S. and Canada), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Saudi Arabia, and Rest of Middle East & Africa) |
| Key Companies Profiled | Glencore plc (Switzerland), Fortum Corporation (Finland), Umicore NV (Belgium), Li-Cycle Holdings Corp. (Canada), Lithion Recycling Inc. (Canada), Tata Chemicals Limited (India), SNAM S.A.S. (France), Ascend Elements, Inc. (U.S.), ACE Green Recycling, Inc. (Singapore), Redwood Materials, Inc. (U.S.), Primobius GmbH (Germany), Attero Recycling Pvt. Ltd. (India), ACCUREC Recycling GmbH (Germany), Trishulavel Eshan Pvt. Ltd. (India), BatX Energies Pvt. Ltd. (India), MTB GROUP (France), and Duesenfeld GmbH (Germany) |
Report overview
Segments covered: type, source, process, model, material. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
The growth of the EV battery recycling market is primarily driven by the growing demand for Electric Vehicles (EVs), stringent regulations for battery recycling, and growing concerns over the depletion of raw materials used in EV battery production. However, safety concerns related to the handling and transportation of used batteries restrain the growth of this market.
Furthermore, government incentives aimed at encouraging the recycling of batteries and ongoing advances in battery recycling technologies are anticipated to generate growth opportunities for market stakeholders. However, the high costs of recycling electric vehicle batteries remain a major challenge for market players.
Additionally, rising investments in recycling infrastructure, particularly in developing countries, is a prominent trend in this market.
Market dynamics
4 factors across 3 forcesIncreasing Concerns over the Depletion of Raw Material Resources Driving Market Growth
The conservation of vital natural resources has become imperative in today’s world, characterized by the growing demand for battery-powered devices and Electric Vehicles (EVs). The production of EV batteries requires substantial amounts of rare and valuable materials such as cobalt, nickel, and lithium. However, these materials are finite, and mining is expensive, with a significant environmental footprint.
According to Redwood Materials (U.S.), electrification is projected to increase the demand for lithium-ion batteries by over 500% by 2030. Furthermore, according to IEA (France), in 2022, the demand for lithium exceeded its supply despite a 180% increase in production since 2017. In 2022, EV battery manufacturing accounted for about 60% of the global demand for lithium, 30% of the demand for cobalt, and 10% of the demand for nickel. Five years earlier, in 2017, these shares were around 15%, 10%, and 2%, respectively. The mining and processing of these critical minerals requires a rapid scale-up to support the energy transition, not only for EVs but also for clean energy technologies.
The lithium, nickel, cobalt, and copper used in EV batteries have to be mined, which has a significant environmental impact. Hence, battery recycling infrastructure and capabilities require improvements to reduce the need to mine these materials. Millions of tons of batteries are expected to be decommissioned over the coming decades. By recycling the battery packs of end-of-life electric vehicles, materials can be extracted and reused to make smaller batteries (if the materials are usable) or battery components. Thus, EV battery recycling can reduce the need for new mining operations as the requirement for these materials will be reduced. Battery recycling not only helps conserve these precious resources but also reduces the environmental toll associated with their mining and processing.
Rising Demand for Electric Vehicles Driving the Need to Recycle EV Batteries
The growing availability of charging infrastructure, government incentives for EV adoption, the decreasing total cost of EV ownership, and strategic developments in the EV industry are driving the adoption of electric vehicles across the globe. According to the World Economic Forum (Switzerland), in 2022, the global sales of electric cars increased by around 60% compared to 2021, exceeding 10 million units for the first time. According to a recent report by the International Energy Agency (IEA), in 2022, one in every seven passenger cars bought globally was an EV. In contrast, in 2017, just one in every 70 new cars sold was an EV. In addition, according to the Net Zero Emissions (NZE) by 2050 scenario, in 2030, electric car fleets are expected to account for approximately 60% of new car sales, with a volume of 300 million units.
Batteries or energy storage systems are essential for all electric vehicles, including Hybrid Electric Vehicles (HEVs) and Plug-in Hybrid Electric Vehicles (PHEVs). The widespread adoption of EVs requires adequate battery manufacturing and supply. EV batteries have a limited lifespan and eventually need to be replaced, resulting in a significant number of used batteries that need to be disposed of.
Electric vehicle batteries contain valuable materials such as lithium, cobalt, nickel, and manganese, which are limited resources. Recycling these materials helps conserve resources and reduce the need to mine and extract new materials, which can be costly and environmentally damaging. EV manufacturers require a lot of batteries, including lithium-ion batteries, to meet the growing demand for electric vehicles and continue the EV movement. Several companies are undertaking initiatives to cater to the growing demand for raw materials, achieve net-zero emissions goals, and reduce the amount of waste generated by EV batteries. Therefore, as EV adoption continues to grow, the recycling of used batteries is expected to become increasingly important to reduce the environmental impact of EVs and ensure the long-term sustainability of the EV industry.
Table of contents
13 chapters · 139 sections · 330 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Battery Type | Lithium-ion Batteries | — |
| By Battery Source | E-bikes | Commercial vehicles |
| By Recycling Process | Pyrometallurgical Process | Hydrometallurgical process |
| By Business Model | Contractual Recycling Services | — |
| By Material | Graphite | Lithium |
By Battery Type
- The lithium-ion batteries segment is expected to account for the largest share of 78.3% of the EV battery recycling market.
- The large market share of this segment can be attributed to the growing demand for electric vehicles, the rising need to manage the disposal of used batteries, the rapid depletion of raw material resources, and stringent regulatory frameworks for battery recycling.
- This segment is also projected to record the highest growth rate during the forecast period 2024–2031.
By Battery Source
- The E-bikes Segment to Dominate the EV Battery Recycling Market in 2024
- The e-bikes segment is expected to account for the largest share of 64.8% of the EV battery recycling market.
- The large market share of this segment can be attributed to the rising adoption of e-bikes worldwide as a convenient and efficient alternative for short-distance commuting, increasing environmental concerns, a shift toward greener transportation, and increasing government incentives and subsidies for e-bike adoption.
- However, the commercial vehicles segment is projected to register the highest growth rate during the forecast period 2024–2031.
- The growth of this segment is driven by the high demand for electric public transportation and logistics services, the surging need to manage the disposal of used batteries, the increasing demand for low-emission commuting, and the increasing government focus on implementing zero-emission commercial transportation.
By Recycling Process
- The pyrometallurgical process segment is expected to account for the largest share of 42.6% of the EV battery recycling market.
- The large market share of this segment is attributed to the high recycling efficiency of the pyrometallurgical process, the increasing need to remove organic material from Li-ion batteries, the need for efficient and cost-effective recycling methods, the increasing need to recover valuable materials from used Li-ion batteries to reduce reliance on new mining operations, stringent environmental regulations, and the growing demand for scalable and flexible recycling processes.
- However, the hydrometallurgical process segment is projected to witness the highest growth rate during the forecast period 2024–2031.
- The growth of this segment is driven by the increasing need to extract a wide range of materials, including copper, lithium, silver, nickel, and zinc, from EV batteries, the increasing need to address the shortage of critical raw materials, and the growing need to lower energy consumption, reduce waste, and minimize the environmental impact of recycling processes.
By Business Model
- The contractual recycling services segment is expected to account for the dominant share of over 86.0% of the EV battery recycling market.
- The large market share of this segment can be attributed to the growing government incentives and regulatory compliance requirements for battery recycling, the increasing need to manage the disposal of used batteries, the rising demand for more efficient and effective recycling through contractual partnerships, enterprises’ increasing need to manage and mitigate liabilities related to the handling, processing, and disposal of hazardous materials, and the rising need to reduce raw material costs in the manufacturing of new batteries.
- This segment is also projected to register the higher CAGR during the forecast period.
By Material
- The Graphite Segment to Dominate the EV Battery Recycling Market in 2024
- The graphite segment is expected to account for the largest share of 18.5% of the EV battery recycling market.
- The large market share of this segment is attributed to its high recycling rate from Sealed Lead Acid (SLA) batteries and the increasing need to recover valuable materials from used EV batteries to reduce the need for mining new resources.
- Additionally, the widespread use of graphite as a key material in battery anodes, combined with ongoing research to improve its recyclability, also contributes to the significant market share of this segment.
- However, the lithium segment is projected to witness the highest growth rate during the forecast period 2024–2031.
- The growth of this segment is driven by the increasing R&D and innovation in lithium-ion batteries, the rising demand for Electric Vehicles (EVs), and the growing need to address the shortage of critical raw materials in EV battery production.
Geographic analysis
Asia-Pacific
Largest shareIn 2024, Asia-Pacific is expected to account for the largest share of 69.1% of the EV battery recycling market, followed by Europe, North America, Latin America, and the Middle East & Africa. Asia-Pacific's significant market share can be attributed to increasing investments in advanced recycling technologies and processes in countries including China, South Korea, and Japan to recover valuable metals and materials from used EV batteries, the high adoption of electric mobility, rising concerns regarding depleting precious and rare-earth metals, and the increasing implementation of new policies and regulations to promote the recycling of EV batteries and reduce environmental pollution. Asia-Pacific to Dominate the EV Battery Recycling Market in 2024
Middle East & Africa
Fastest growthHowever, the Middle East & Africa is slated to register the highest growth rate of 45.4% during the forecast period. The growth of this regional market is driven by the growing demand for lithium-ion batteries for EV production and the increasing volume of battery waste generated.
Competitive landscape
- May 2024
Attero Recycling Pvt. Ltd. (India) announced plans to invest over ₹8,000 crore in ramping up its e-waste and battery recycling capacity over the next five years.
- October 2023
Stellantis N.V. (Netherlands) signed an MoU with Orano SA (France) to establish a joint venture for recycling end-of-life electric vehicle batteries and scrap from gigafactories in Europe and North America. The joint venture was aimed at producing black/active mass.
- October 2023
RACE Energy (Telangana), a battery swapping company, partnered with LOHUM CLEANTECH (Uttar Pradesh), a Li-ion battery manufacturer, recycler, and second-life battery solutions provider, to tackle EV battery waste and explore second-life applications for its used batteries.
- May 2023
LOHUM Cleantech, Private Limited. (India) forged an academic R&D partnership with the Indian Institute of Technology (IIT), Kanpur (India), to advance the sustainability of Li-ion batteries.
- April 2023
Fortum (Finland) opened Europe's largest closed-loop hydrometallurgical battery recycling facility in Finland.
- January 2023
The UAE government announced plans to develop its first recycling plant for electric vehicle batteries to support green mobility, achieve its net-zero emissions goal by 2050, and create a circular economy.
- June 2022
Lithium Battery Recycling Solutions (LBRS) (U.K.), a part of the Cawleys Group (U.K.), partnered with Voi Technology (U.S.), a provider of e-scooters, to dispose of and recycle end-of-life batteries from electric vehicles.
- Glencore plc · Switzerland
- Fortum Corporation · Finland
- Umicore NV · Belgium
- Li-Cycle Holdings Corp. · Canada
- Lithion Recycling Inc. · Canada
- Tata Chemicals Limited · India
- SNAM S.A.S · France
- Ascend Elements, Inc. (U.S.)
- ACE Green Recycling, Inc. · Singapore
- Redwood Materials, Inc. (U.S.)
- Primobius GmbH · Germany
- Attero Recycling Pvt. Ltd. · India
- ACCUREC Recycling GmbH · Germany
- Trishulavel Eshan Pvt. Ltd. · India
- BatX Energies Pvt. Ltd. · India
- MTB GROUP · France
- Duesenfeld GmbH · Germany
Frequently asked questions
The EV battery recycling market study focuses on market assessment and opportunity analysis based on revenues and developments across the segments and subsegments of the EV battery recycling market in various regions and countries. The study also includes a competitive analysis based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies adopted in the last three to four years.
Cite this report
Meticulous Research. (2024). EV Battery Recycling Market - Global Opportunity Analysis And Industry Forecast (2024-2031) (Report No. MR-799). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ev-battery-recycling-market-5483