Natural Food Colors Market (2026-2036)
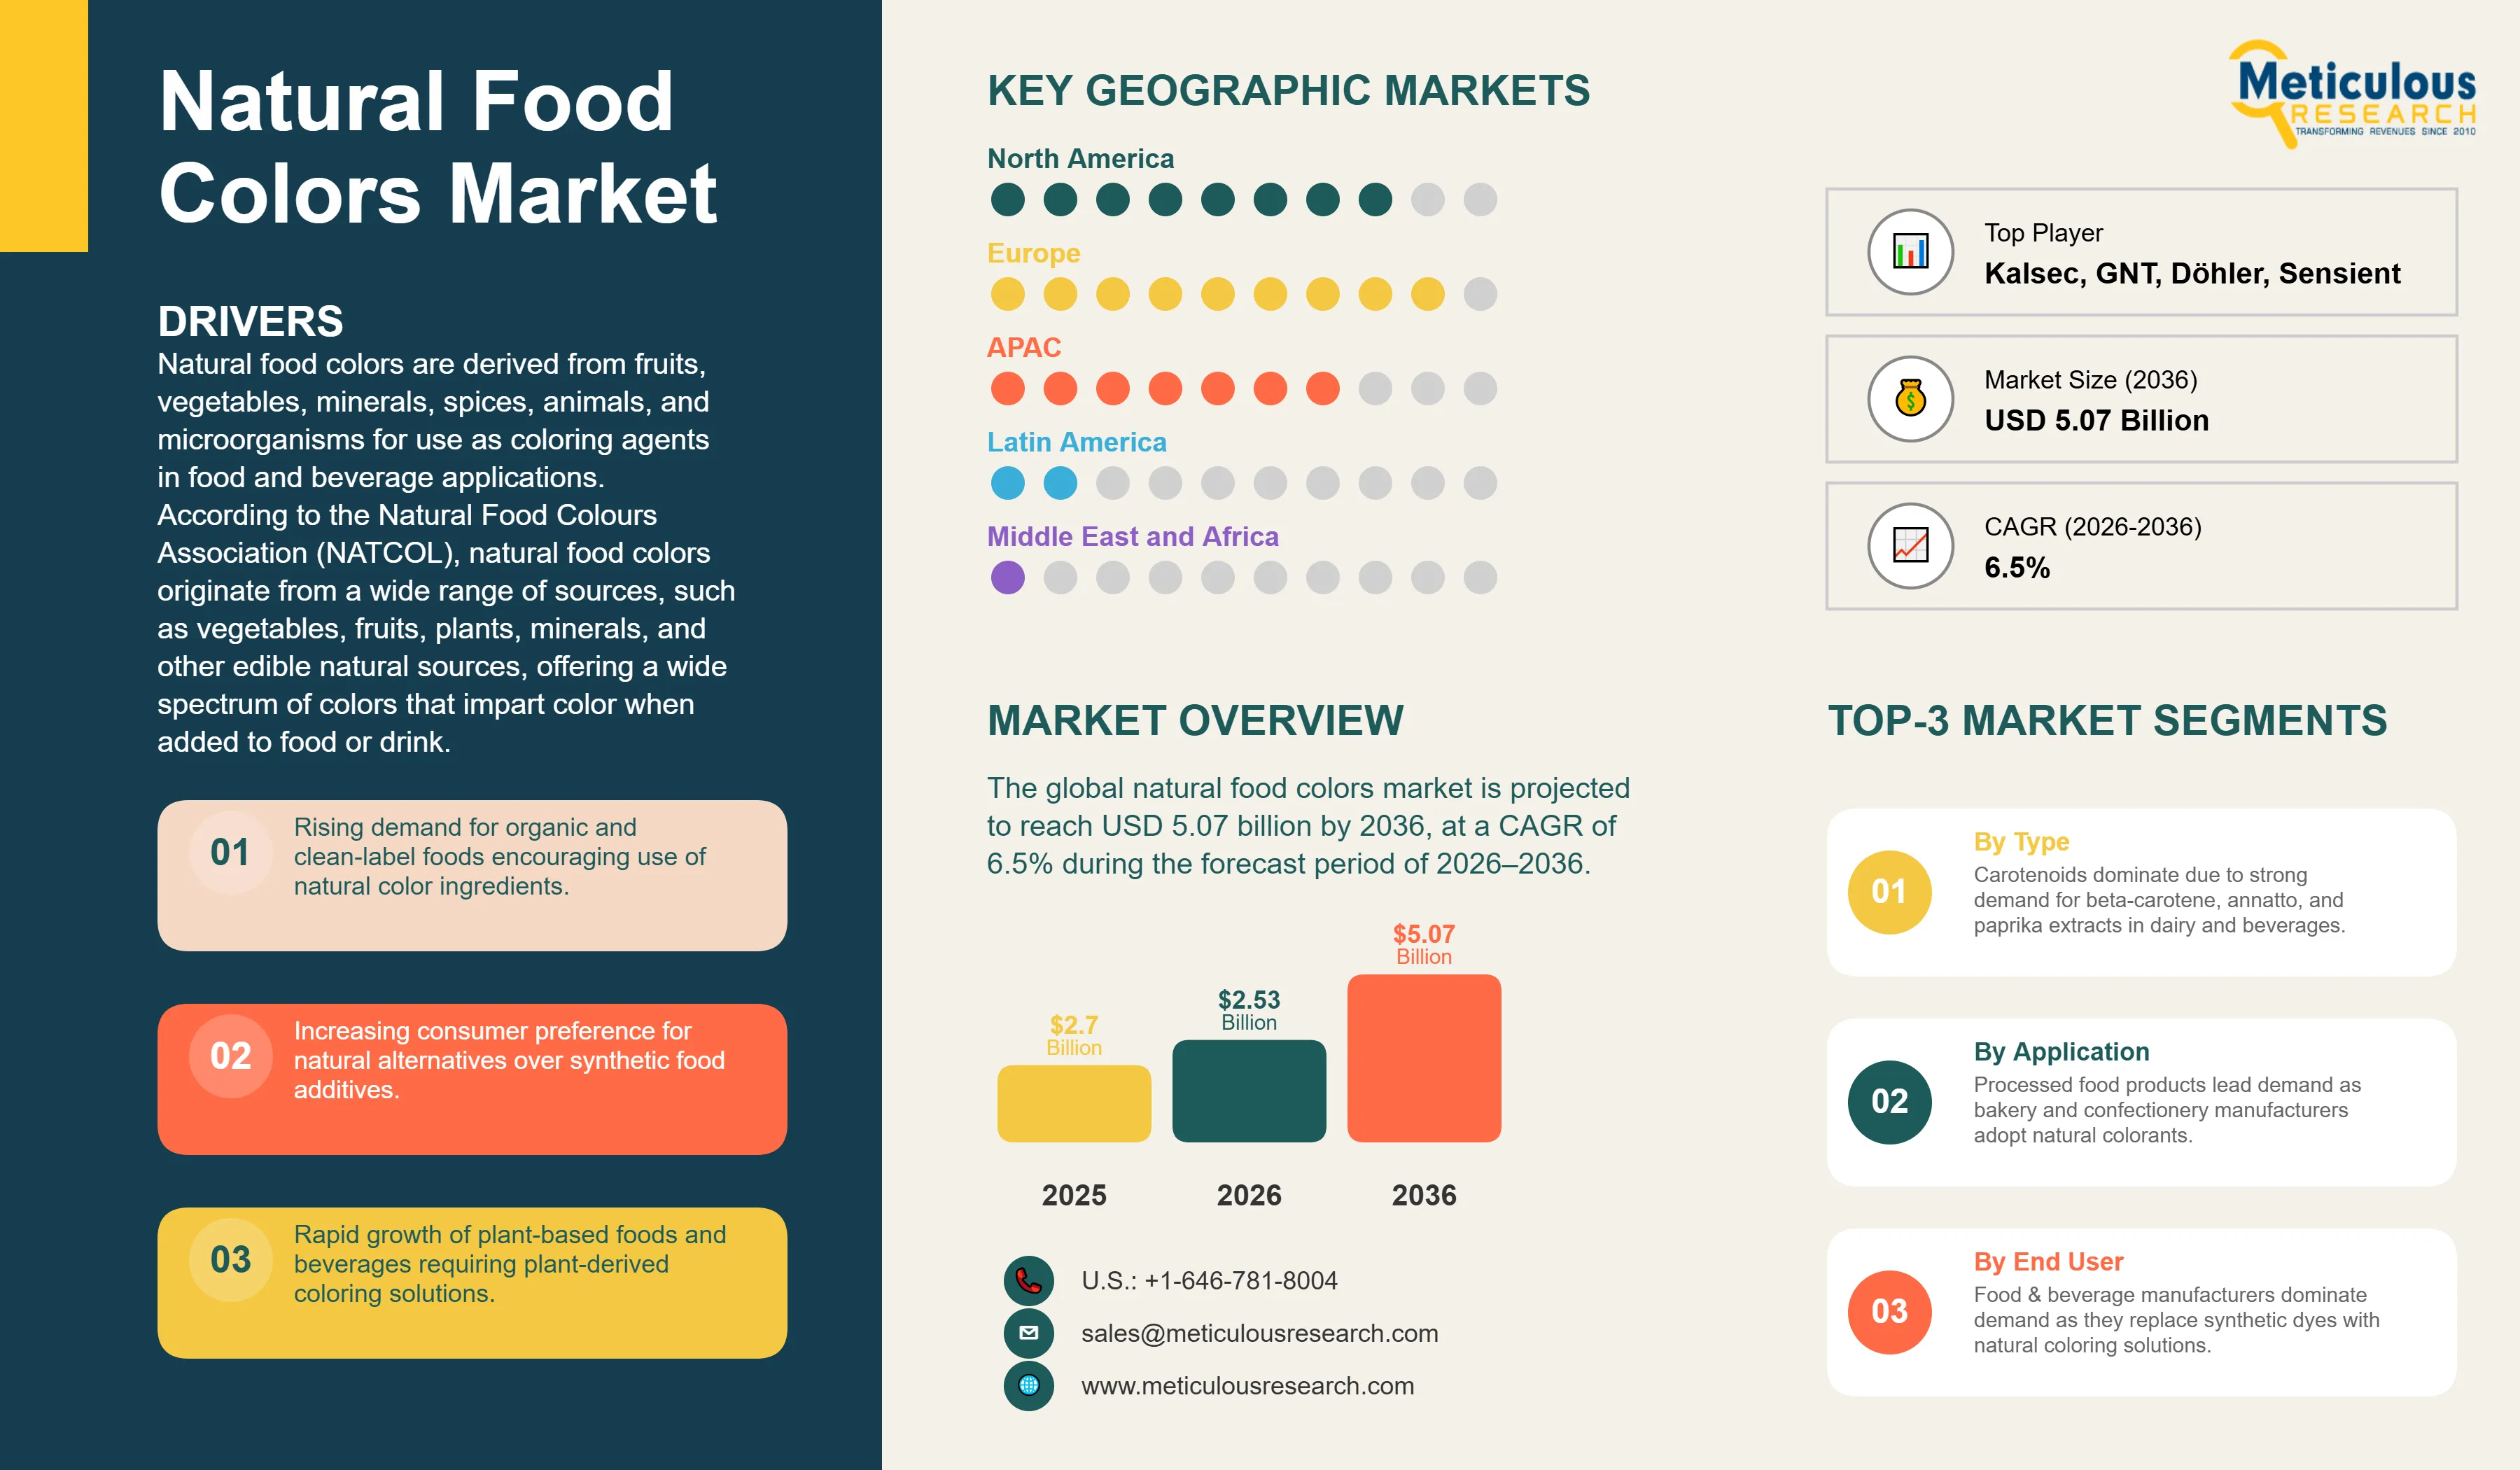
The global natural food colors market was valued at USD 2.53 billion in 2025. This market is projected to reach USD 5.07 billion by 2036 from USD 2.7 billion in 2026, at a CAGR of 6.5% during the forecast period of 2026–2036. In terms of volume, the market is projected to reach around 252,600 tons by 2036, growing at a CAGR of 5.1% during the forecast period.
- Published
- Mar 2026
- Pages
- 362
- Format
- PDF + Excel
- Report ID
- MR-389
- Base year
- 2025
- 2025 · BASELINE
- $2.53B
- 2036
- $5.07B
- CAGR 2026–2036
- 6.5%
2025 baseline · 2026–2036 forecast at 6.5% CAGR · hover a bar for the value
Key highlights
The global natural food colors market is projected to reach USD 5.07 billion by 2036, growing at a CAGR of 6.5% during the forecast period of 2026–2036.
In terms of volume, the market is projected to reach approximately 252,600 tons by 2036, growing at a CAGR of 5.1% during the forecast period.
Based on type, the carotenoids segment is expected to account for the largest share of the natural food colors market in 2026, driven by strong demand for beta-carotene, paprika extract, and annatto across dairy, bakery, and beverage applications. The phycocyanin segment is projected to grow at the fastest CAGR during the forecast period, driven by increasing demand for natural blue pigments derived from spirulina in beverages, confectionery, and functional foods.
Based on source, the plant-based segment is expected to dominate the market in 2026 due to the widespread availability and commercial maturity of plant-derived pigments such as turmeric, paprika, beetroot, and annatto. The microorganism-derived segment (including algae, fungi, and bacteria) is poised to grow at the fastest CAGR, driven by expanding commercial production of spirulina- and fermentation-derived pigments.
Based on form, the liquid segment is expected to account for the largest share of the natural food colors market in 2026 due to its ease of incorporation in beverage, dairy, and confectionery formulations and its compatibility with large-scale food processing systems. Liquid formulations are also expected to register strong growth during the forecast period.
Based on solubility, the water-soluble segment is expected to dominate the market in 2026, driven primarily by increasing use in beverages such as soft drinks, juices, flavored waters, and sports drinks.
Based on application, the processed food products segment is expected to account for the largest share of the natural food colors market in 2026, with bakery and confectionery products representing the largest sub-segment. The beverages segment is projected to record the highest growth during the forecast period due to increasing demand for clean-label ingredients in functional beverages and flavored drinks.
Europe is expected to account for the largest share of the global natural food colors market in 2026, driven by strong regulatory restrictions on synthetic colorants and high consumer demand for clean-label food ingredients.
Asia-Pacific natural food colors market is expected to grow at the fastest CAGR during the forecast period, driven by expanding food processing industries and increasing adoption of natural ingredients across China, India, and Southeast Asia.
In April 2025, the U.S. FDA announced plans to phase out petroleum-based synthetic food dyes, a policy direction expected to significantly increase demand for natural food color alternatives across the U.S. food and beverage industry.
Report summary
| Particulars | Details |
|---|---|
| Report Coverage | Details |
| Market Size (Value) by 2036 | USD 5.07 Billion |
| Market Size (Volume) by 2036 | ~252,600 Tons |
| Market Size (Value) in 2025 | USD 2.53 Billion (estimated) |
| Market Size (Value) in 2026 | USD 2.7 Billion |
| Market Growth Rate (Value) | CAGR of 6.5% (2026–2036) |
| Format | PDF, Excel & Cloud Portal · 362 pages |
| Market Growth Rate (Volume) | CAGR of 5.1% (2026–2036) |
| Dominating Region | Europe |
| Fastest Growing Region | Asia-Pacific |
| Dominating Type Segment | Carotenoids |
| Fastest Growing Type Segment | Phycocyanin |
| Dominating Source Segment | Plants |
| Fastest Growing Source Segment | Microorganisms |
| Dominating Form Segment | Liquid |
| Fastest Growing Form Segment | Liquid |
| Dominating Solubility Segment | Water-soluble |
| Fastest Growing Solubility Segment | Water-soluble |
| Dominating Application Segment | Processed Food Products |
| Fastest Growing Application Segment | Beverages |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | By Type: Carotenoids (Beta Carotene, Annatto, Lutein, Lycopene, Canthaxanthin, Astaxanthin, Other Carotenoids); Anthocyanins; Caramel; Chlorophyll; Curcumin; Betanin; Carmine; Phycocyanin; Other Natural Food Colors By Source: Plants; Minerals; Microorganisms; Animals By Form: Liquid; Powder; Other Forms By Solubility: Water-soluble; Oil-soluble By Application: Processed Food Products (Bakery & Confectionery; Meat, Poultry & Seafood; Dairy; Snacks & Cereals; Oils & Fats; Other); Beverages (Non-alcoholic: Carbonated Soft Drinks, Juice & Juice Concentrates, Dairy & Dairy Alternative Beverages, Other; Alcoholic Beverages) |
| Countries Covered | North America (U.S., Canada); Europe (Germany, France, U.K., Italy, Spain, Rest of Europe); Asia-Pacific (China, Japan, India, Australia, Rest of Asia-Pacific); Latin America (Brazil, Mexico, Argentina, Rest of Latin America); Middle East & Africa |
| Key Companies | Oterra A/S (Denmark), Givaudan SA (Switzerland), Sensient Technologies Corporation (U.S.), Archer-Daniels-Midland Company (U.S.), DSM-Firmenich AG (Switzerland), BASF SE (Germany), Lycored, Ltd (Israel), Döhler Group (Germany), GNT Group B.V. (Netherlands), San-Ei Gen F.F.I., Inc. (Japan), Kalsec, Inc. (U.S.), Innovation Colour Technology S.L. (Spain), IFC Solutions (U.S.), Mane Kancor Ingredients Private Limited (India), and Kolorjet Chemicals Pvt Ltd. (India) |
Report overview
Segments covered: type, source, form, solubility, application. Regions: North America, Europe, Asia-Pacific, Latin America.
Natural food colors are derived from fruits, vegetables, minerals, spices, animals, and microorganisms for use as coloring agents in food and beverage applications. According to the Natural Food Colours Association (NATCOL), natural food colors originate from a wide range of sources, such as vegetables, fruits, plants, minerals, and other edible natural sources, offering a wide spectrum of colors that impart color when added to food or drink. Key types include carotenoids, anthocyanins, chlorophyll, curcumin, carmine, spirulina (phycocyanin), and betanin.
Market dynamics
5 factors across 3 forcesRising Demand for Organic Food Products
The rapidly growing global organic food market is a primary driver of natural food color demand, as organic products by definition exclude synthetic colorants and therefore rely exclusively on natural color solutions to maintain visual appeal after processing.
The global organic food market is poised to grow at a CAGR of 10.1% from 2025 to reach USD 324.1 billion by 2032. The growth of this market is primarily attributed to the growing number of health-conscious consumers, increasing demand for clean-label products, and support of both government and non-government organizations for organic farming.
Organic foods are produced without synthetic fertilizers, pesticides, growth hormones, or antibiotics and are free from genetically modified organisms (GMOs), with natural food colors used extensively to enhance visual appeal while maintaining organic certification compliance. Governments across major markets are actively supporting the growth of organic agriculture and food production through subsidies, certification programs, labeling requirements, and procurement policies, creating regulatory and institutional support for the demand for organic food. The growing availability and accessibility of organic products through both mainstream and specialty retail channels is broadening the organic consumer base beyond early adopter demographics, further driving the market for natural food colors used in organic product formulation.
Increasing Preference for Clean-Label Food Products
The growing consumer preference for clean-label food products is one of the most significant trends driving demand for natural food colors. Clean-label products typically feature simple, recognizable ingredient declarations and minimal processing, aligning with consumer demand for transparency and natural ingredients in packaged foods and beverages. Consumers increasingly perceive synthetic additives and complex chemical ingredient names as undesirable, prompting food manufacturers to reformulate products using naturally derived ingredients.
Industry surveys highlight the strength of this trend. For example, the Ingredion ATLAS 2024 global consumer insights study reports that around 78% of consumers globally are willing to pay more for food and beverage products labeled as natural or clean-label, reflecting the commercial importance of such positioning for food manufacturers.
Natural food colors derived from fruits, vegetables, plants, and algae enable manufacturers to replace synthetic dyes with ingredients that can be declared in a more consumer-friendly manner on product labels. In many cases, these ingredients are labeled according to their botanical source (e.g., “black carrot concentrate,” “turmeric extract,” or “spirulina extract”) rather than synthetic color codes such as FD&C or E-number designations, improving label transparency.
As a result, many multinational food and beverage companies have been increasingly reformulating product portfolios to eliminate artificial colorants and replace them with natural alternatives. In addition, retailer-driven clean-label requirements, particularly in private-label product ranges, are driving the adoption of natural food colors across processed food, dairy, confectionery, and beverage applications. These factors collectively contribute to the growing demand for natural food colors globally.
Table of contents
13 chapters · 142 sections · 362 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Type | Carotenoids | Phycocyanin |
| By Source | Plants | Microorganisms |
| By Form | Liquid | — |
| By Solubility | Water-Soluble | Water-soluble |
| By Application | Processed Food Products | Beverages |
By Type
- The carotenoids segment is expected to account for the largest share of the global natural food colors market in 2026.
- Carotenoids are a diverse group of natural pigments that produce yellow, orange, and red hues and include widely used food colorants such as beta-carotene, lutein, lycopene, astaxanthin, and paprika oleoresin.
- These pigments are typically derived from plant sources, microalgae, or fermentation processes and are widely used across dairy, bakery, confectionery, and beverage applications.
- The largest share of this segment is supported by several factors, including their broad regulatory acceptance across global food markets, established production technologies, and multifunctional benefits as both colorants and nutritional ingredients.
- Certain carotenoids, such as beta-carotene (a provitamin A compound), lutein, and lycopene, are also associated with nutritional and antioxidant properties, increasing their attractiveness for use in functional foods and beverages.
- In addition, technological advancements in fermentation-based production and extraction technologies have improved supply reliability and cost efficiency for carotenoid pigments.
- The phycocyanin segment is poised to grow at the fastest CAGR during the forecast period of 2026–2036.
- This growth is driven by phycocyanin’s unique commercial position as one of the few naturally derived blue pigments used in food applications, typically produced from spirulina (Arthrospira platensis).
- Increasing demand for natural blue shades in confectionery, beverages, and dairy applications, combined with growing consumer preference for natural ingredients, continues to drive strong demand for phycocyanin-based color solutions.
By Source
- The plants segment is expected to account for the largest share of the natural food colors market in 2026.
- Plant-derived pigments are the most commercially mature category of natural colorants, with established sources including fruits, vegetables, roots, flowers, spices, and seeds.
- Examples include anthocyanins from black carrot and purple sweet potato, curcumin from turmeric, chlorophyll from leafy plants, and carotenoids from paprika and marigold flowers.
- Plant-derived colors offer broad coverage across the visible color spectrum and align strongly with clean-label, vegan, and plant-based food positioning, which increasingly influences ingredient selection among food manufacturers.
- These factors have contributed to the widespread adoption of plant-based pigments across processed food, beverage, and dairy applications.
- The microorganisms segment is expected to grow at the fastest CAGR during the forecast period.
- Growing commercial interest in algae-derived pigments (such as spirulina-derived phycocyanin) and fermentation-produced colorants is driving innovation in this segment.
By Form
- The liquid segment is expected to dominate the global natural food colors market in 2026.
- Liquid formulations are widely used in food and beverage manufacturing due to their ease of incorporation, accurate dosing capability, and compatibility with automated production systems.
- Liquid natural colors are well-suited for beverages, dairy products, and confectionery applications, where homogeneous dispersion and consistent color distribution are essential.
- In addition, liquid formats often allow better solubility and stability in aqueous food systems, making them the preferred option in many industrial food production environments.
- The strong growth of beverage applications further drives the dominance of liquid color formulations in the market.
By Solubility
- Water-Soluble Segment Dominates Across Both Share and Growth
- The water-soluble segment is expected to account for the largest share of the natural food colors market in 2026 and is also projected to record the highest growth during the forecast period.
- This dominance reflects the fact that many of the largest food color application categories, such as beverages, dairy products, confectionery, and bakery products, are primarily water-based systems requiring water-soluble pigments.
- Increasing demand for naturally colored soft drinks, juices, functional beverages, and dairy beverages is further driving the demand for water-soluble color solutions.
- Advances in formulation technologies, including water-dispersible carotenoid emulsions and improved stabilization techniques for pigments such as anthocyanins and phycocyanin, are also contributing to the growth of this segment.
By Application
- The processed food products segment is expected to account for the largest share of the global natural food colors market in 2026.
- Within this segment, bakery and confectionery products are the largest sub-segment, driven by the strong visual importance of color in products such as candies, gummies, icing, and chocolate coatings.
- Increasing consumer demand for visually appealing products and the ongoing reformulation of processed foods to replace synthetic dyes with natural alternatives are key factors supporting the dominance of this segment.
- The beverages segment is expected to grow at the fastest CAGR during the forecast period of 2026–2036.
- Growth in this segment is driven by increasing demand for clean-label beverages, functional drinks, plant-based beverages, and naturally colored sports and energy drinks.
- Both non-alcoholic beverages (including soft drinks, juices, and dairy alternatives) and alcoholic beverages are increasingly incorporating natural color solutions as manufacturers shift away from synthetic dyes.
Geographic analysis
Europe
Fastest growthThis is mainly attributed to a strong regulatory environment governing food additives, high consumer awareness of clean-label ingredients, and a well-developed food processing industry. Europe is also home to several major natural food color manufacturers, including Oterra A/S, GNT Group B.V., DSM-Firmenich AG, BASF SE, Givaudan SA, and Döhler Group, among others. Europe Leads; Asia-Pacific Fastest Growing
North America
Largest shareNorth America is the second-largest regional market, with the U.S. accounting for the majority of regional demand. Increasing consumer concern over synthetic food additives and the growing adoption of clean-label product formulations continue to drive demand for natural food colors across the region.
Asia-Pacific
The Asia-Pacific region is projected to register the highest growth during the forecast period. Rising consumer awareness of natural ingredients, rapid expansion of the food processing industry, and increasing demand for clean-label products are driving adoption across China, India, Japan, South Korea, and Southeast Asia.
Latin America
Latin America and the Middle East & Africa natural food colors markets are smaller but steadily expanding markets, driven by urbanization, rising disposable incomes, and growing consumption of processed foods and beverages.
Competitive landscape
- Archer-Daniels-Midland Company
- DSM-Firmenich AG
- BASF SE
- Döhler Group
- Lycored Ltd.
- San-Ei Gen F.F.I., Inc.
- Kalsec, Inc.
- Mane Kancor Ingredients Private Limited
Frequently asked questions
The global natural food colors market is estimated at USD 2.53 billion in 2025 and is projected to reach USD 2.70 billion in 2026, growing to USD 5.07 billion by 2036, at a CAGR of 6.5% during 2026–2036. In terms of volume, the market is projected to reach approximately 252,600 tons by 2036, growing at a CAGR of 5.1%.
Cite this report
Meticulous Research. (2026). Natural Food Colors Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-389). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/reports/natural-food-colors-market-5088